Roof Insurance Claim Help in Roanoke, TX
47% of Texas Claims Are Denied — We Help Roanoke Homeowners Fight Back
Nearly 47% of homeowner insurance claims in Texas are closed without payment. The five largest insurance companies denied or closed more than 44% of claims without payment in 2025, and deductibles rose 22% in that same year. If you’re a Roanoke homeowner dealing with a denied roof claim, an underpaid settlement, or an adjuster who classified obvious storm damage as “wear and tear” — you have options. Roanoke Roofing Pros provides hands-on insurance claim assistance from initial documentation through final approval, including denied claim appeals, re-inspection coordination, and guidance on the Texas appraisal clause.
How We Help With Your Roof Insurance Claim
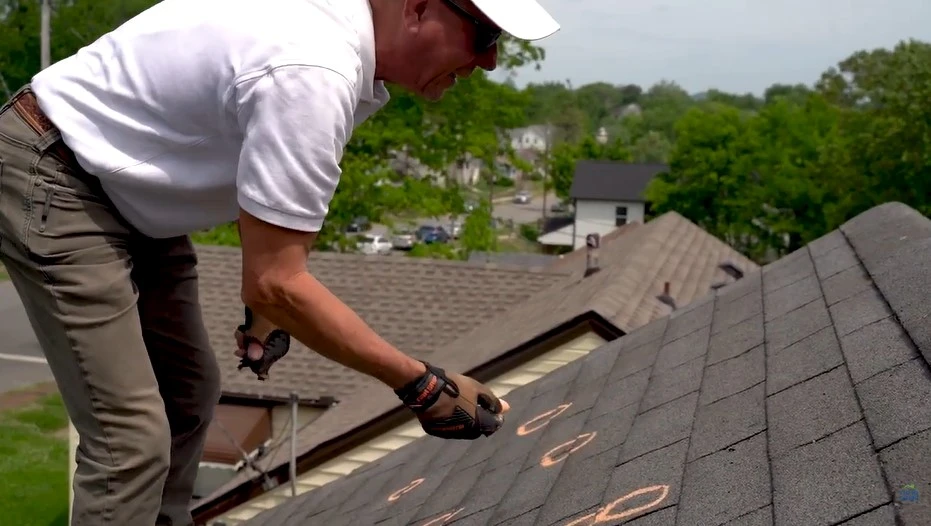
Step 1: Free Photo-Documented Inspection. We perform a 45-minute inspection of your entire roofing system, counting hail impacts per test square, documenting damaged components, and photographing every finding. This report becomes the foundation of your insurance claim — and it’s yours to keep regardless of whether you hire us.
Step 2: Claim Filing Assistance. We help you file your claim with the right documentation from the start. Many claims are denied because homeowners file without professional evidence. Our photo reports, test-square counts, and component assessments give your claim the documentation it needs to be taken seriously.
Step 3: Adjuster Meeting Attendance. When your insurance company sends their adjuster, we’re there. We walk the adjuster through our findings, point out damage they might miss, and ensure the inspection is thorough. Having a professional present who knows what to look for has helped Roanoke homeowners recover thousands of additional dollars on their claims.
Step 4: Denied Claim Appeals. If your claim is denied, we don’t stop. We prepare supplemental documentation, request re-inspections with different adjusters, and guide you through the Texas appraisal clause process. We’ve successfully reversed multiple denials for Roanoke homeowners — including in Briarwyck where a homeowner’s claim was overturned in 18 days after three neighbors had been approved for the same storm.
Why Do Roof Insurance Claims Get Denied in Texas?
Understanding why claims are denied helps you avoid the common traps:
1. “Wear and tear” classification. The most common denial. Adjusters classify storm damage as pre-existing deterioration. The difference between hail impact (circular bruise with displaced granules) and UV wear (gradual granule erosion) is visually distinct to a trained inspector — but adjusters sometimes conflate them, intentionally or not.
2. Insufficient documentation. Claims filed without professional inspection reports, test-square counts, or component assessments are easy to deny. Insurance companies know that most homeowners don’t have the evidence to contest a denial.
3. Cosmetic damage exclusions. Some Texas policies now include “cosmetic damage” exclusions that allow insurers to deny hail claims unless the damage is “functionally” compromising the roof. We document functional damage — fiberglass mat fractures, seal strip failures, and active water intrusion pathways — not just surface marks.
4. Missed filing deadlines. Texas gives you one year from the date of the storm to file. Homeowners who wait too long lose their right to claim entirely — even if the damage is severe.
5. Lowball settlements. Some claims are “approved” but for far less than the actual repair cost. The insurance company acknowledges damage but underestimates the scope, materials, or labor required. These underpaid claims can be challenged through supplemental documentation or the appraisal process.
What Is the Texas Appraisal Clause?
The appraisal clause is your most powerful tool when you disagree with your insurance company’s damage assessment. Most Texas homeowner policies include it, and here’s how it works:
You hire an independent appraiser. This is a licensed professional who inspects your roof and determines the full scope and cost of the damage — independent of your insurance company’s assessment.
Your insurance company hires their appraiser. Both appraisers then attempt to agree on the damage scope and cost.
If they disagree, a neutral umpire decides. Both appraisers select a mutually agreed-upon umpire whose decision is binding.
The appraisal process frequently results in significantly higher payouts than the insurance company’s original assessment — often 2x to 3x the initial offer. We guide Roanoke homeowners through this process and can recommend qualified independent appraisers.
Your Rights as a Texas Homeowner
Right to file within one year. You have 12 months from the storm date to file a claim. Don’t let an adjuster tell you the deadline has passed unless you’re certain of the storm date.
Right to choose your own contractor. Your insurance company cannot require you to use a specific roofer. You choose who repairs or replaces your roof — not them.
Right to a re-inspection. If you disagree with the adjuster’s findings, you can request a second inspection. We prepare supplemental documentation and attend the re-inspection.
Right to invoke the appraisal clause. If you and your insurer disagree on the damage scope or cost, the appraisal clause provides a binding resolution process outside of litigation.
Right to file a TDI complaint. The Texas Department of Insurance investigates complaints against insurers. If your claim is being improperly handled, TDI can intervene.
Important: It is illegal in Texas for any contractor to offer to “waive your deductible” or cover the deductible cost. Any contractor who makes this offer is committing insurance fraud. We never make this offer — and you should walk away from any contractor who does.
Frequently Asked Questions About Roof Insurance Claims
Why was my roof insurance claim denied?
The most common reasons are “wear and tear” classification, insufficient documentation, cosmetic damage exclusions, and missed filing deadlines. We help Roanoke homeowners challenge denials with supplemental evidence, re-inspections, and the Texas appraisal clause.
Should I call a roofer or insurance first after a hailstorm?
Call a roofer first. A professional inspection with photo documentation gives you evidence before filing. If we find the damage doesn’t warrant a claim, we’ll tell you — saving you from an unnecessary claim on your CLUE report.
How long do I have to file a roof claim in Texas?
One year from the date of the storm. We recommend filing as soon as possible after inspection confirms damage. Waiting reduces your chances of approval as insurance companies can argue the damage occurred after the claimed storm.
My neighbors got approved but my claim was denied — why?
Different insurance companies have different adjusters with different thresholds. This is one of the most common frustrations in Roanoke. We’ve reversed denials in exactly this scenario by providing supplemental documentation that clearly distinguishes storm damage from normal wear.
Will filing a claim raise my insurance rates?
Hail claims are generally “Act of God” claims in Texas and should not raise individual rates. However, widespread storm damage in a region can lead to area-wide rate adjustments. Not filing a legitimate claim means paying premiums for coverage you’re not using.
What is the difference between RCV and ACV policies?
RCV (Replacement Cost Value) pays the full cost to replace your roof with similar materials. ACV (Actual Cash Value) deducts depreciation based on age. RCV policies provide significantly higher payouts. Check your policy declarations page or call your agent to confirm which type you have.
Can a roofer waive my deductible?
No. It is illegal in Texas for any contractor to waive, absorb, or pay a homeowner’s insurance deductible. This constitutes insurance fraud. Any contractor who offers to waive your deductible is breaking the law and should be avoided.
Don’t Accept a Denied Claim Without a Fight
47% of Texas claims are denied — but denial isn’t the end. We help Roanoke homeowners document damage, challenge denials, and get the coverage they’ve been paying for.
📍 211 James St, Roanoke, TX 76262 · Mon–Sun 8AM–5PM · Open 7 Days